Cash discount
0%processing-cost target*
Build processing costs into your posted card price and give customers a discount when they pay cash.
- A genuine discount from the posted price
- Clear pricing before checkout
- Program eligibility reviewed with you
Keep more of what you work for. Explore smarter payment processing, the right POS, and a pricing model that fits your business.
 Tap. Pay. Keep moving.
Start with how you want to handle processing costs. We’ll help you compare the whole picture.
Build processing costs into your posted card price and give customers a discount when they pay cash.
Add a disclosed fee to eligible credit-card purchases to recover part of your acceptance cost.
Show the cash price and the full card price side by side, so customers know their total before paying.
Compare these traditional models. All rates and account fees are discussed on your call.
Network interchange and assessments, plus an agreed processor markup. Costs vary with the card and transaction.
An agreed percentage and/or per-transaction fee. In-person, keyed and online payments may have different rates.
A monthly fee plus network costs and agreed transaction fees. Compare the total against your payment volume.
Transactions fall into rate categories. Review qualification rules and the full effective cost, not only the advertised starting rate.
From a full POS to a compact terminal, let’s find a setup that works where you work.
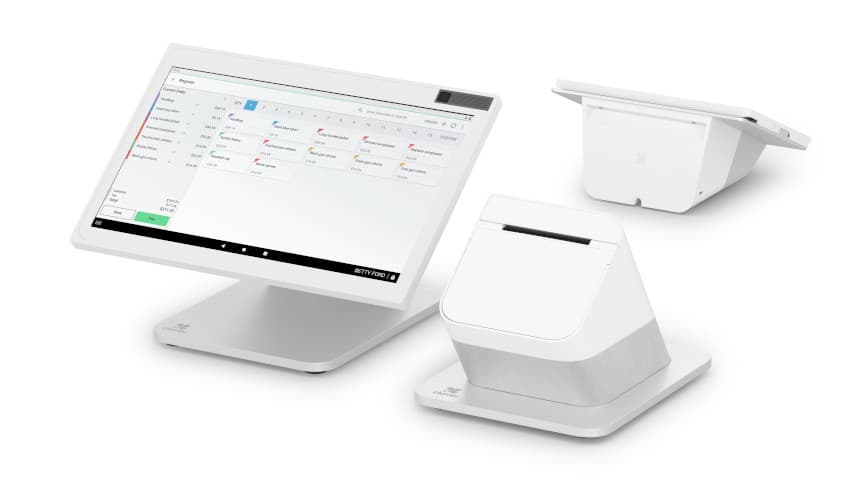
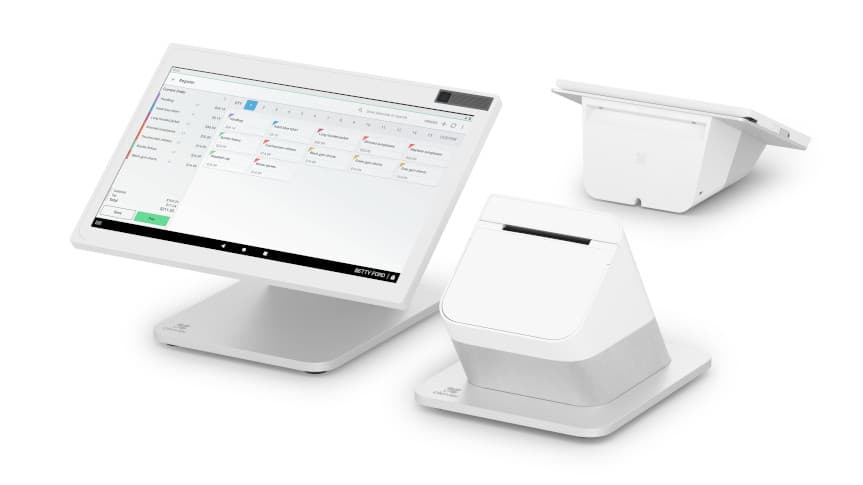
A countertop POS for sales, orders, and everyday business management.
Ask about this setup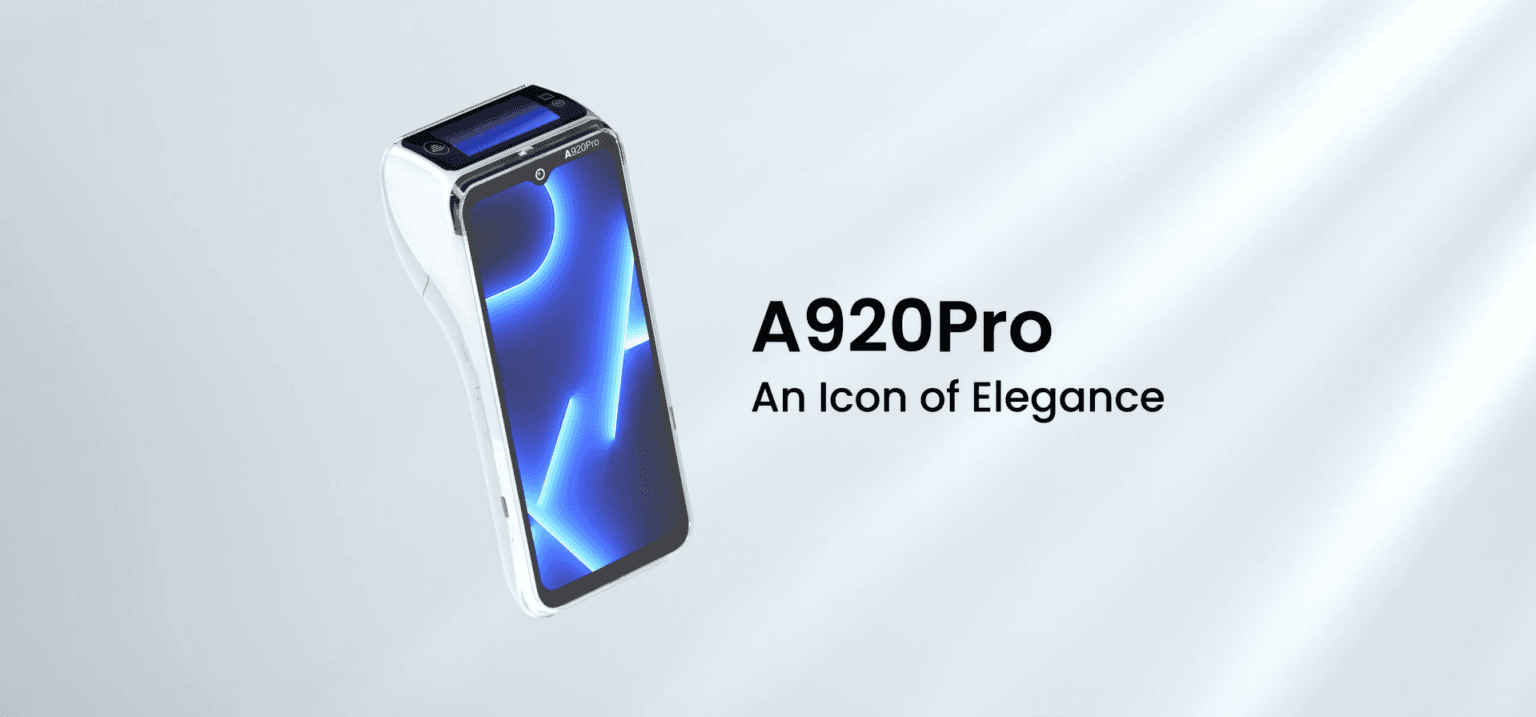
Explore portable smart terminals for flexible checkout around your business.
Ask about this setup
Countertop payment terminals for everyday card and contactless transactions.
Ask about this setupIllustrative hardware options. Model, stock, processor compatibility, software and pricing are confirmed during your consultation. Brand names and images identify their respective products; they do not imply an unconfirmed partnership.
Explore an example using your card volume and credit-card mix.
At the default inputs, 3.50% − (75% × 3%) = 1.25%. This is an example, not a quoted rate or guaranteed saving.
Review my actual statementPlanning estimate only. Assumes the entered credit share is eligible, the surcharge is permitted, and processing costs stay constant. Excludes additional monthly, equipment, per-transaction and surcharge-processing costs. Your credit acceptance cost, state rules and processor determine the allowed surcharge. Debit and prepaid transactions are never surcharged.
| What matters | Cash discount / dual pricing | Surcharge | Traditional pricing |
|---|---|---|---|
| Customer sees | Posted card price and a cash discount or cash price | A disclosed fee on eligible credit purchases | One sale price, no program surcharge |
| Merchant cost | Eligible processing costs may be offset | Part of credit acceptance cost can be recovered | Merchant pays the agreed processing charges |
| Debit / prepaid | No added card fee; follow approved posted-price setup | Never surcharged | Merchant pays applicable fees |
| Best starting point | Review posted prices and customer experience | Review credit mix, location and acceptance costs | Compare total costs at your sales volume |
Share your volume, location, current setup, and goals.
Review models, account fees, equipment, and written terms.
Move forward after eligibility and processor approval, with setup guidance.
Talk it through with our team in English or Bangla.
Let’s have a conversationNo. The cash discount program aims to offset eligible processing charges through properly posted prices. Monthly service, hardware, software, chargeback, and other account fees may remain. Your written proposal will show the applicable costs before you decide.
That outcome is possible in an illustration, but it is not a quote. The result depends on your current cost, eligible credit volume, debit mix, and additional fees. For example, 3.5% current cost minus a 3% surcharge on 75% of sales leaves 1.25% before additional costs. Use the calculator to explore the assumptions.
Debit and prepaid cards cannot be surcharged under Visa and Mastercard rules, even when a debit card is run as credit. Surcharge availability and disclosure requirements vary by location. We review your business location and the processor’s requirements before proposing a program.
Tell us what you use and what you need. The devices shown are examples. Availability, model, software, processor compatibility, purchase or lease terms, and any equipment charges are confirmed during your consultation.
We can discuss an online gateway, virtual terminal, invoicing, recurring billing, and ACH alongside in-person payments. Availability, setup, security responsibilities, and transaction fees depend on the approved provider and your business.
A personal review. Clear options. A decision that’s yours.